

 1
The dispute regarding the CLARITY Act has become a straightforward question: will Americans choose to keep their cash in banks or will they use dollar-pegged stablecoins with promising rewards?
Before the Tuesday Senate vote, eight banking organizations requested that lawmakers to establish stricter regulations regarding incentives for using stablecoins. Their position is simple: when deposits leave the banks, they lose a reliable and inexpensive source of funding and availability of cash.
The importance of this question arises from the fact that banks use deposits to provide loans. In May, Cryptopolitan wrote that in the U.S. banks use about 80% of deposits to finance loans; therefore, the matter of stablecoin incentives becomes the matter of both funding costs and control of dollar-based payments.
Why holding tokens instead of cash is the whole ballgame
Stablecoins are made to mimic such assets as the dollar. According to a paper published by BIS, almost 98% of stablecoins are valued in dollars. IMF says that the value of the market is about $300 billion in August.
The 2025 GENIUS Act prevents the issuers of stablecoins from providing interest or yield directly. The analysis from the White House showed that the legislation does not explicitly ban distribution of rewards by affiliates and other third parties. The CLARITY Act could determine how much room those arrangements have to continue.
What the banks want struck from the text
In a letter released on Monday addressed to Senate Majority Leader John Thune and Senate Minority Leader Chuck Schumer, banking groups said they could not back the latest rewards proposal.
They also urged the Senate to eliminate the word “solely” from the definition of payment based on holding, to replace the phrase “economically or functionally equivalent” with the word phrase “substantially similar”, and to remove references to rewards being based on balance, duration or time in business.
Organizations that put their name to the letter also include the American Bankers Association, Bank Policy Institute, and Independent Community Bankers of America, among others. The letter comes after 80 state bankers’ associations joined calls for stricter language on September 10, according to the ABA Banking Journal.
The government’s own math undercuts the panic
The White House Council of Economic Advisers (CEA) came up with a significantly lower estimate of possible damage to lending.
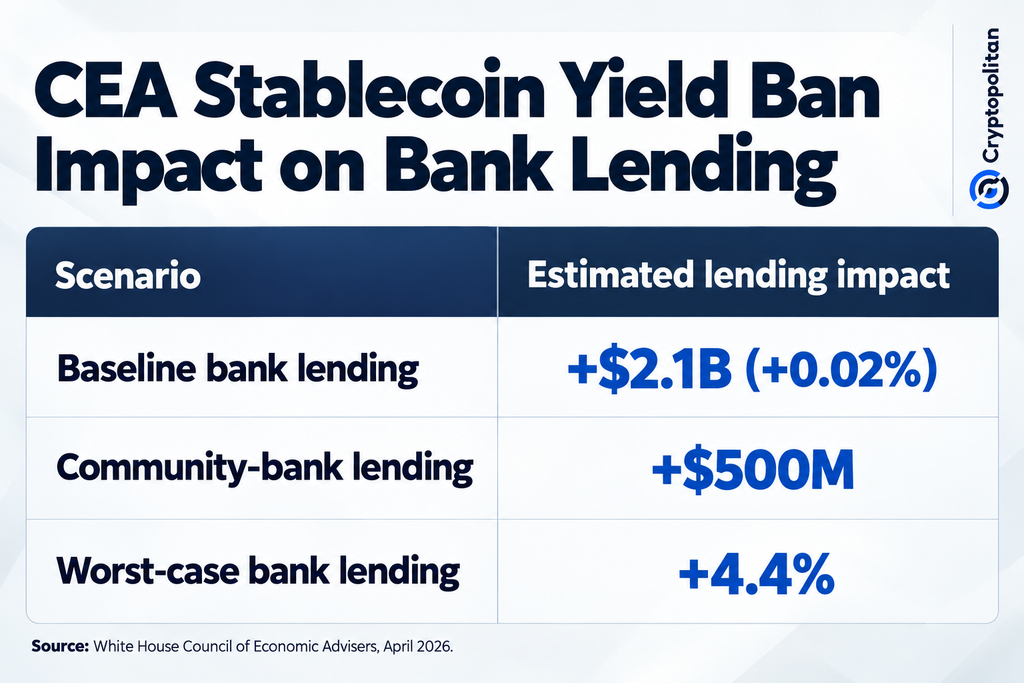
Its April study indicated that banning the stablecoin yield would boost the level of lending by banks by only $2.1 billion, being equal to 0.02%, while creating a net welfare loss of $800 million. Lending of the community banks would increase by approximately $500 million.
Even in the case of nearly unrealistic assumptions that the CEA mentioned, including stablecoin usage of around six times higher than today’s and transformation of the Fed’s monetary policy, the increase in bank lending is estimated at only 4.4%.
What changed since the May draft
The updated legislation issued on Sunday has 126 significant amendments sought by the Democrats, as reported by Reuters.
The bill tightens rules governing how public figures can benefit from cryptocurrencies and grants state attorneys general significant powers regarding law enforcement in this area. Senator Cynthia Lummis stated that the bill is now ready to go ahead, while Senator Elizabeth Warren’s staff described the changes dealing with ethics as “empty.”
The bill requires 60 votes to pass the cloture rule on Tuesday.
Why the bank-versus-crypto framing is too simple
The industry split is not so clear-cut. According to Cryptopolitan, Goldman Sachs, BNY and Morgan Stanley supported the legislation, defying retail-oriented banking groups.
Meanwhile, community banks are not necessarily rejecting stablecoins. Moov’s community bank and credit union network of over 1,000 institutions is able to utilize stablecoin payment technology provided by Coinbase.
This impact goes further than the banking industry of the U.S. The BIS cautions that the use of dollar-pegged stablecoins widely may promote digital dollarization in emerging economies, while the IMF informs that even small-scale use of stablecoins may compel old-fashioned financial firms to up their game in terms of competition in costs and efficiency.
Therefore, the vote on Tuesday is not merely a disagreement about deposits, but rather a battle for who will take control of the next phase of dollar payments.
| Issue | May Senate Banking version | Sept. 14 final text |
|---|---|---|
| Passive stablecoin yield | Prohibited | Still prohibited |
| Activity/transaction rewards | Permitted | Explicitly permitted |
| Rewards that function like bank interest | Prohibited | Prohibited |
| Treasury role | No special deposit “circuit breaker” in the May summary | Treasury gets a new circuit-breaker mechanism |
| Community banks | General concern over deposit competition | Explicitly protected through the circuit breaker |
| Measurement of deposit impact | No comparable detailed mechanism | Federal agencies must study deposit flows and lending effects |
| Marketing stablecoins as deposits | Restricted | Explicitly prohibited |

 cointelegraph.com

 coinpedia.org
 1


 coindesk.com